Disclaimer: Information found on CryptoreNews is those of writers quoted. It does not represent the opinions of CryptoreNews on whether to sell, buy or hold any investments. You are advised to conduct your own research before making any investment decisions. Use provided information at your own risk.
CryptoreNews covers fintech, blockchain and Bitcoin bringing you the latest crypto news and analyses on the future of money.

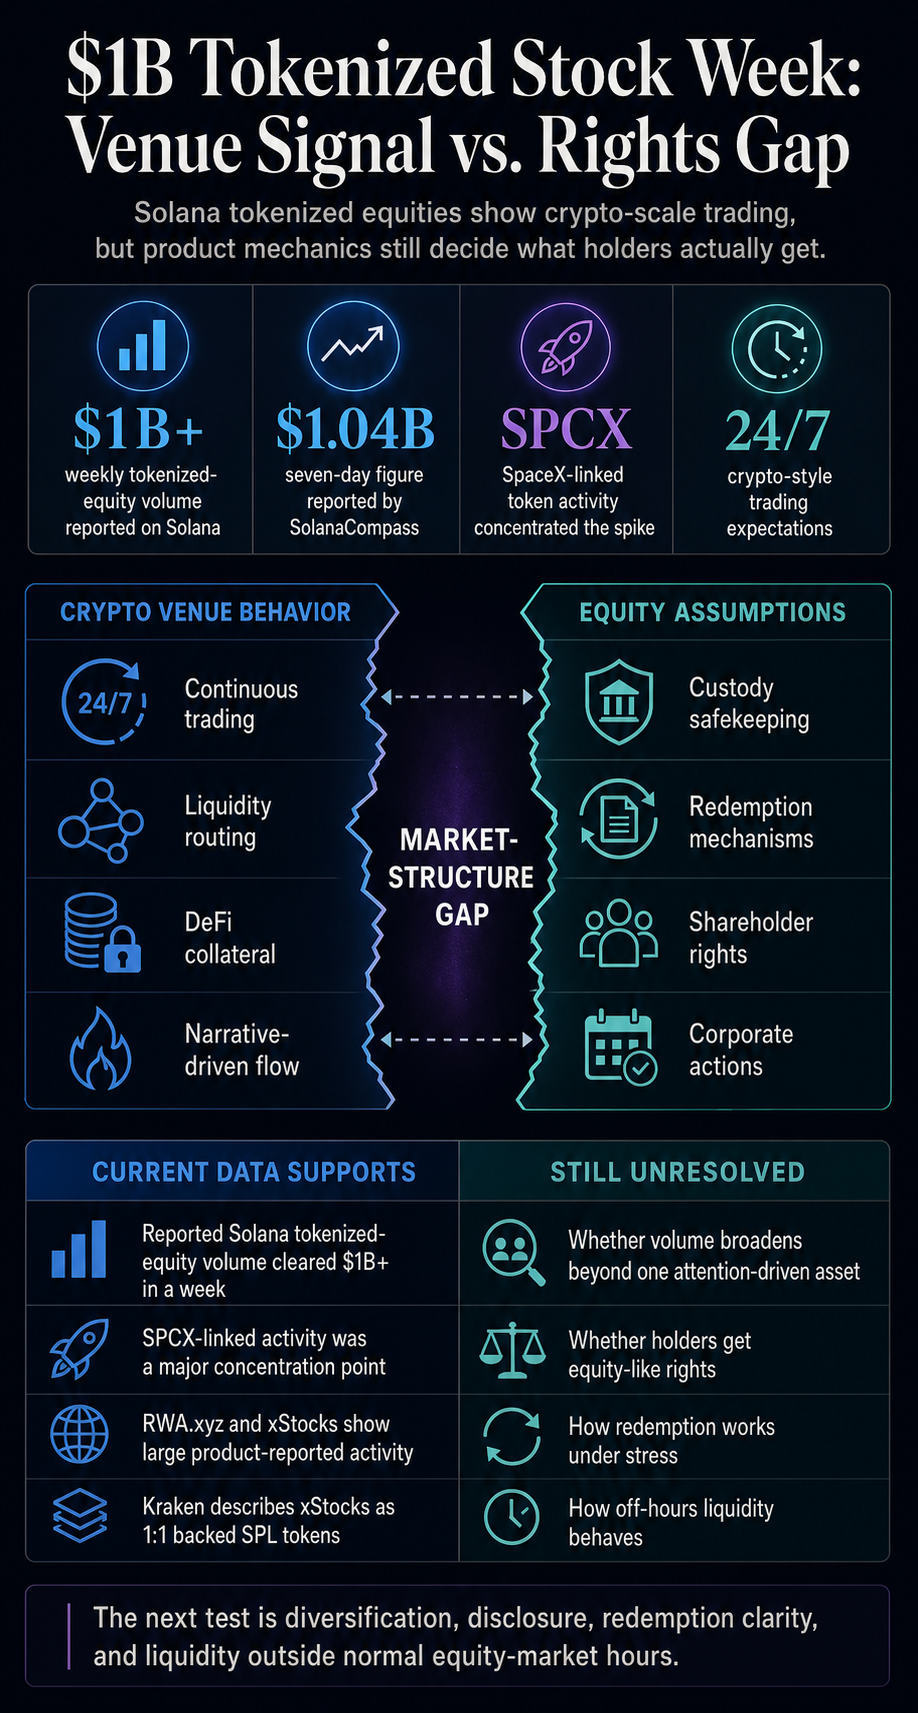
Solana’s tokenized equities have crossed a significant threshold, reporting more than $1 billion in weekly volume and establishing a market that now operates like a live cryptocurrency trading venue.
According to ecosystem messaging, tokenized equities on the Solana network cleared over $1 billion in weekly volume on June 20. This milestone demonstrates that equity-like tokens are generating crypto-scale trading flows, even though their ownership, redemption, and liquidity structures do not yet fully mirror those of public stocks.
This shift extends beyond a single chain or token. Tokenized stocks are beginning to function as a 24/7 crypto trading venue. Users can chase exposure, liquidity providers can route flow, and platforms can market continuous access to assets that remain linked to off-chain companies, brokerage relationships, market hours, and legal terms.
However, this gap between crypto trading habits and traditional equity mechanics is where the risk lies. The recent surge was heavily clustered around SpaceX-linked SPCX activity rather than representing a broad basket of tokenized equities. SolanaCompass attributed the volume surge primarily to SPCX, with the strongest support concentrated around Backpack/SPCX trading pairs.
While this indicates strong demand, it limits what a headline figure like $1 billion can reveal about diversified tokenized-stock adoption. A single attention-heavy private-market proxy can make a new venue appear deeper and more mature than it actually is.
Related Reading
SpaceX’s IPO Exposes the First Crack in Tokenized Stocks – Fragmented Ownership and Allocation
SpaceX is exposing the first major flaw in tokenized stocks: while everyone can trade the name, not everyone owns the same underlying asset.
Jun 13, 2026 · Gino Matos
The Venue Signal
The most significant change is behavioral. Tokenized equities have moved beyond the theoretical promise that traditional assets can move on-chain. They now resemble instruments traded with crypto habits: fast turnover, narrative-driven demand, cross-venue routing, and expectations of access outside normal stock-market rhythms.
Data from RWA.xyz’s tokenized stocks dashboard and the Solana network dashboard anchors this shift. These metrics show sufficient activity to make market-structure issues unavoidable, even though the origins of trade, product differences, and long-term durability remain unresolved.
Once a stock-linked token can trade with crypto-style velocity, users may begin to expect crypto-style entry and exit mechanisms, even when the underlying reference asset follows a very different rulebook.
The xStocks ecosystem reports more than $25 billion in total transaction volume across its tokenized-equities network. Additionally, data from the RWA.xyz platform showed Solana holding hundreds of millions of dollars in xStocks distributed asset value on June 25.
These figures are based on product and dashboard data, with maturity still unresolved. However, they are large enough to make the category harder to dismiss as merely a demo market.
Related Reading
Solana’s xStocks Top $1.6B in First Month of Trading, Largely Driven by Centralized Exchanges
After an initial launch surge, xStocks cooled on-chain as Tesla topped holder lists and assets under management (AUM) stabilized.
Jul 30, 2025 · Gino Matos
This functional change underpins the $1 billion weekly volume. A small or experimental Real-World Asset (RWA) product can rely on education, disclaimers, and limited user expectations. A high-volume trading venue, however, must withstand users treating the instrument as something they can enter, exit, borrow against, and price continuously.
| What current data supports | Open limitation |
|---|---|
| Solana and SolanaCompass reported more than $1 billion in weekly tokenized-equity volume. | Distribution across a broad basket of tokenized stocks remains unresolved. |
| SPCX-linked activity was a major concentration point in the reported week. | SpaceX remains separate from the tokens; secondary-market trading leaves issuer status unchanged. |
| RWA.xyz and xStocks data show large product-reported activity. | Each product still needs its own legal, economic, and redemption analysis. |
| Kraken describes xStocks as 1:1 backed and issued as SPL tokens on-chain. | Holders still need clear product-specific explanations of shareholder rights. |
SPCX Turns Demand Into A Concentration Test
SPCX illustrates both sides of the market simultaneously. The SpaceX-linked token gives traders exposure to a private company narrative that would otherwise be difficult for many crypto users to access.
Related Posts
This represents the demand side. It also concentrates activity on a single attention-heavy asset, highlighting the market-structure problem.
CryptoSlate’s prior coverage of SPCX tokenized-stock risk already demonstrated why these details matter. A token linked to SpaceX exposure is a different instrument from actual SpaceX shares, and the practical result depends on how the product is issued, backed, redeemed, allocated, and transferred.
This distinction becomes increasingly important as volume rises because more users are likely to treat the instrument as stock-like, even when the rights package differs.
There is also a venue-quality issue. Recent CryptoSlate coverage of Solana trading-flow incentives framed the chain’s push for professional order flow as a test of whether liquidity will remain once incentives and attention shift elsewhere.
Tokenized equities now face the same test. A week dominated by one narrative asset can prove that users will trade, but it leaves unanswered whether liquidity is broad, resilient, or easy to redeem against under stress.
This difference is crucial for off-hours trading. Crypto markets trade continuously. Equity markets, corporate actions, broker-dealer processes, custody arrangements, and transfer-agent systems still operate on different clocks.
If tokenized equities trade heavily while the underlying equity market is closed or while a private-market reference asset has limited price discovery, the token market can create its own price expectations before the off-chain machinery can respond.
The same mismatch can appear in spreads, collateral rules, and market-maker behavior. If the token price moves while the reference market is closed, traders may treat the token as price discovery, while issuers and brokers still need traditional processes to handle backing, redemption, or corporate actions.
This is manageable when volume is small. At over $1 billion in reported weekly activity, it becomes a venue-level design issue.
Rights And Redemption Decide What The Volume Means
The next phase of the tokenized stock market will be decided less by whether users want the products and more by whether users understand what they are buying.
Kraken’s support documentation states that xStocks are 1:1 backed by the underlying equity and issued as on-chain SPL tokens. This is a meaningful product claim and differs from pure synthetic exposure.
However, the same category still requires careful language because tokenized exposure can give users economic tracking while leaving ordinary shareholder rights, direct claims, or simple redemption expectations dependent on specific product terms. CryptoSlate previously covered this broader point in the context of crypto stock tokens and shareholder status.
The $1 billion week is as much a disclosure test as a volume headline. If tokenized stocks are going to trade like crypto, users need plain answers regarding who holds the underlying exposure, what happens to dividends or corporate actions, who can redeem, how redemption works, which jurisdictions are eligible, and what happens when liquidity disappears outside traditional market hours.
Related Reading
Tokenized Stocks as DeFi Collateral Arrive Before the Borrowing Risk Is Settled
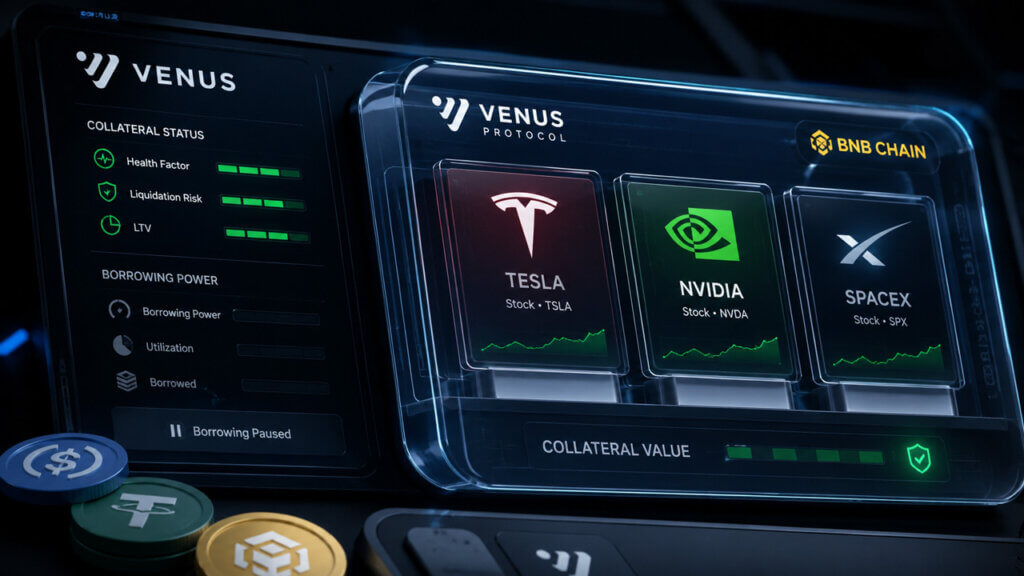
Venus added Tesla, Nvidia, and SpaceX-linked bStocks as collateral, while borrowing, pricing, and liquidation risks remain untested.
Jun 22, 2026 · Liam ‘Akiba’ Wright
Once tokenized stocks are used as collateral, the question expands from whether a token can track a stock to whether lending markets, liquidation systems, oracles, and users can survive the mismatch between 24/7 crypto liquidation logic and equity-market reference assets.
CryptoSlate’s coverage of tokenized stocks entering DeFi collateral markets highlights why this issue moves quickly from product design into risk management.
For Solana, the opportunity is clear. The chain has become a venue where tokenized equities can find visible volume, and its low-cost, high-throughput design fits the trading behavior these products invite.
The question is whether tokenized equity markets can sustain that activity once traders look beyond a single SpaceX-linked proxy and begin asking equity-like questions.
The next signal is diversification. If volume broadens across a larger set of tokenized stocks, if disclosures become standardized, and if redemption and custody mechanics are easy to understand before users trade, the $1 billion week will look like an early sign of durable market structure.
If activity remains concentrated around one narrative asset, it will look more like venue-finding demand before the market has agreed on what tokenized stock ownership should mean.
The post Solana hits $1B in weekly tokenized stock trading as demand for hard-to-access equities surge appeared first on CryptoSlate.
