Disclaimer: Information found on CryptoreNews is those of writers quoted. It does not represent the opinions of CryptoreNews on whether to sell, buy or hold any investments. You are advised to conduct your own research before making any investment decisions. Use provided information at your own risk.
CryptoreNews covers fintech, blockchain and Bitcoin bringing you the latest crypto news and analyses on the future of money.

The European Securities and Markets Authority (ESMA) seeks to extend Europe’s restrictions on non-compliant stablecoins beyond trading activities to include the services that allow customers to hold and move their assets. If adopted as proposed, this change would eliminate the option for users to keep such tokens with a licensed custodian once their trading pairs are delisted.
In its September 30, 2026 response to a review of the EU’s Markets in Crypto-Assets regulation (MiCA), ESMA has asked the European Commission to prohibit every licensable crypto-asset service involving stablecoins that fail to meet the regulation’s applicable requirements. Custody and transfers are explicitly included in this list of services. The consequence of this proposal would affect existing holders who have ceased trading, as well as new customers seeking to acquire these assets.
This represents a shift from the regulator’s January 2025 approach, which maintained that mere custody and transfer services should remain permissible. While the proposal could give compliant tokens a wider advantage in European distribution, it does not mandate a forced conversion timetable nor does it necessarily trigger a global shift in demand.
The permission left after delisting
ESMA’s January 17, 2025 statement distinguished between services that offered non-compliant stablecoins to the public or admitted them to trading, and those that simply held or transferred them. Under that earlier framework, platforms were expected to stop making the tokens available for trading, and other services had to cease where they constituted an offer to the public.
During that earlier transition, acquisition restrictions were expected by the end of January 2025, with temporary sell-only services remaining available through the end of the quarter.
For investors, the distinction regarding custody was significant. Losing access to a trading pair did not necessarily mean losing the service that safeguarded an existing balance or enabled its withdrawal. ESMA acknowledged that investors retaining those holdings could face worse execution conditions, even while custody and transfer services remained available.
A historical example illustrates this distinction. In its March 3, 2025 reporting, CryptoSlate noted that Binance planned to remove nine tokens’ trading pairs for European Economic Area (EEA) users by March 31, while keeping deposits, withdrawals, conversions, and custody services available. This was the exchange’s announced approach in March 2025.
Related Reading
How MiCA Brings Banks Closer to Controlling Europe’s Stablecoin Access
The September response would replace this activity-by-activity distinction with a broader asset-compliance test. ESMA argues that the lack of a clear prohibition creates disparities between compliant and non-compliant issuers and facilitates regulatory arbitrage.
The scope of this proposal derives from MiCA’s Article 3 definitions. Custody includes safekeeping or controlling clients’ crypto-assets or their means of access, including private keys. Transfers cover moving assets on a client’s behalf from one ledger address or account to another. Both are expressly listed services, with Article 82 setting client-agreement requirements for transfers.
Provider permissions are also distinct from token compliance. Article 59 requires authorization as a crypto-asset service provider, or qualifying permissions for specified financial entities, and states that authorizations must identify the specific services permitted. A license for a provider does not, by itself, determine whether a particular stablecoin can be serviced.
An existing holder would therefore not avoid the proposed restriction by deciding never to trade again. If the wording became law without an exception, the custodian’s continued safekeeping of the asset would itself be covered by the prohibition.
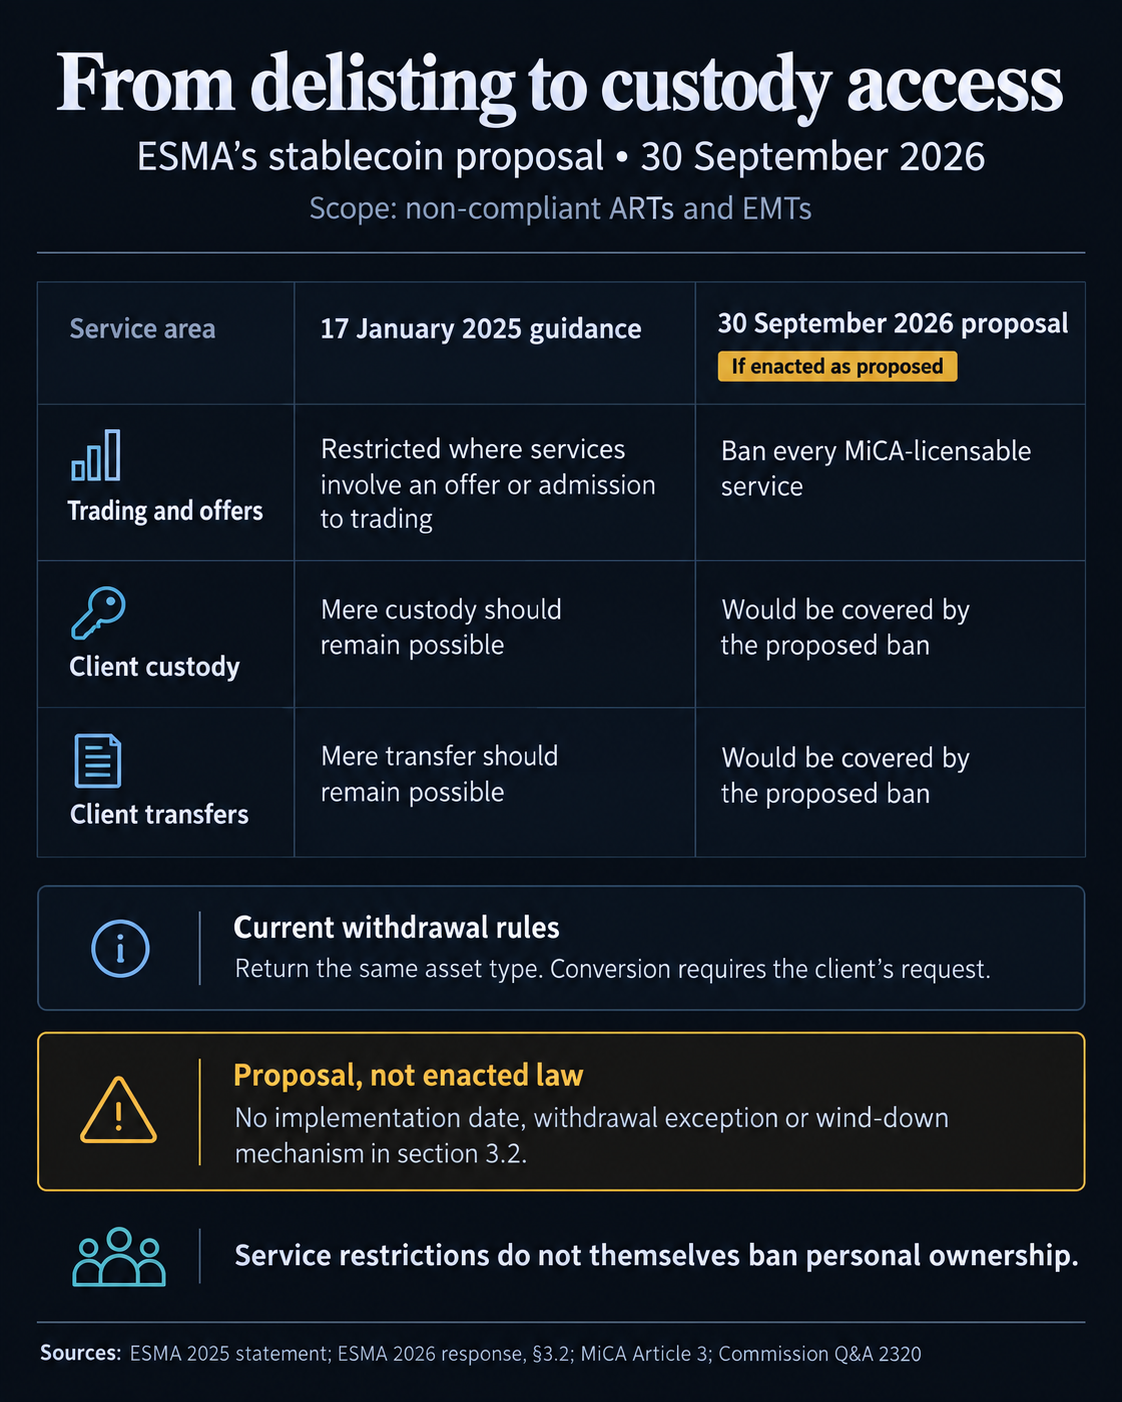
ESMA’s response is a policy submission, not an enacted amendment. The Commission’s consultation had a September 30 deadline, and its page indicates that the resulting review report may, if warranted, be accompanied by a legislative proposal.
Section 3.2 of ESMA’s submission provides no implementation date, withdrawal exception, or wind-down mechanism. This omission is significant because ending custody requires a method to return assets that a provider already controls, while the proposed prohibition also extends to transfer services.
Related Posts
Current custody rules provide a relevant starting point. Article 75 requires procedures to return clients’ crypto-assets or their means of access as soon as possible. Client assets must also be segregated from the provider’s own holdings.
An answer from the European Commission via ESMA, dated February 18, 2026, further states that the assets returned must be of the same type held when the client requests withdrawal. A provider may offer conversion into fiat or another crypto-asset, but the client must request it at withdrawal, and the provider must have permission for the additional service.
This existing interpretation does not fully resolve how a future blanket service restriction would handle exits. It does, however, explain why delisting, termination of custody, and compulsory conversion cannot be treated as interchangeable outcomes. Legislators would need to determine how any new prohibition fits with the obligation to return assets.
The stablecoin proposal targets these professional services. It does not ban personal ownership, order tokens to be frozen, or prescribe compulsory conversion. A holder’s ability to retain an asset and a licensed business’s ability to hold or move it for that customer are distinct questions.
Related Reading
EU Faces September 30 Clock to Decide Future of DeFi Loans
Trading Shares Do Not Measure Custody Exposure
The earlier delistings demonstrate how trading activity can change at European-facing venues without a comparable shift across the wider market.
In a July 2026 paper, Nicola Borri and Kirill Shakhnov examined trading in the dollar-linked tokens USDT and USDC across 14 exchanges selected from CoinMarketCap’s top 30 centralized venues. Their daily pair-volume data from CryptoCompare ran from January 1, 2024, through December 7, 2025.
The authors classified Bitstamp, Coinbase, Gemini, and Kraken as “regulated-facing” because their Similarweb EU audience shares exceeded 10%; all four also had US audience shares above 10%. The other 10 venues were classified as globally oriented, including Binance despite its EEA delistings. This audience proxy identifies neither individual EU-resident trades nor a clean division of legal exposure.
Around the study’s April 1, 2025 event date, the authors estimated that USDC’s share of combined USDT and USDC trading rose by about six percentage points on regulated-facing exchanges relative to global exchanges. The estimate covered a 30-day window and used smoothed, detrended data; it measured a relative trading shift across venue groups.
The authors estimated that USDT trading volume fell by about 20% on regulated-facing exchanges relative to global venues, while the USDC-volume estimate was not statistically significant. USDC gained share primarily because USDT trading contracted in that comparison, not because the study established a corresponding expansion in USDC trading.
Aggregate USDC-to-USDT trading-volume ratios across the sample remained nearly flat around the event. This describes sampled exchange turnover, not worldwide demand or EU custodial balances. The legal documents and study provide no total for the holdings that a future custody restriction could affect.
Related Reading
Europe’s Central Banks Want to Scrap This Stablecoin Reserve Safeguard
If the proposal became law in its present form, compliant tokens could retain access to regulated custody and transfer channels that non-compliant tokens would lose. For customers who want a provider to safeguard and move a dollar-linked balance, compliance could affect the usefulness of that asset beyond the mere availability of a trading pair.
The next consequential text would be a legislative amendment, particularly regarding its scope, application date, and treatment of existing balances. How it reconciles the end of custody with the return of clients’ assets would determine whether and how existing holders must leave regulated services.
The post ESMA proposes ending EU custody and transfer services for non-compliant stablecoins appeared first on CryptoSlate.
